 Capacity Ledger
A Sourcing Manager's Guide to Four Cents of Diesel Relief
Executive Order 14435, published in this morning's Federal Register, defers a federal diesel excise tax from October 5 through December 31. The pump price your freight surcharge is keyed to carries a different one, and the Department of Energy table stepped to 40.0 percent and 79 cents a mile on Wednesday regardless. What the order defers is worth about four cents a mile.
The Internal Revenue Code taxes diesel fuel in two places, and the second one only reaches what the first one missed.
Section 4081 taxes the fuel on removal from a refinery or a terminal. Section 4041 taxes the sale or the use, and 4041(a)(1)(B) lifts it back off any liquid that already paid under 4081.
Executive Order 14435, signed Monday and published in this morning's Federal Register at 91 FR 64747, defers the second one.
"Does that reach the freight line of a delivered price, or does it stop short of it?"
The number your surcharge is keyed to
EIA printed $6.199 a gallon for the week of October 5. That is two weekly falls off the record of $6.529 set the week of September 21, the highest value in a series that starts in March 1994 and runs 1,699 weekly prints.
EIA's own footnote under that table says prices include all taxes. So the 24.4 cents section 4081 puts on a gallon of diesel at the rack, 24.3 under 4081(a)(2)(A) plus the tenth of a cent 4081(a)(2)(B) adds for the Leaking Underground Storage Tank fund, is already sitting inside the $6.199.
Order 14435 never mentions 4081. Nine sections, and the tax in the survey price is not one of them.
So the Department of Energy's CY2026 matrix did on Wednesday what it does every Wednesday. 43.5 percent on LTL and $0.86 a mile on truckload effective September 23, 42.0 percent and $0.83 effective September 30, 40.0 percent and $0.79 effective October 7.
Two days after the order was signed, and for reasons that have nothing to do with it.
What the order does defer
Section 2 postpones the taxes imposed by 4041(a)(1)(A) and 4041(b)(1)(B) on liability incurred October 5 through December 31, with no penalty, interest or addition to tax. Section 2(c) separately directs the IRS to announce that it will not impose the section 6715 penalty when dyed diesel is sold for highway use or used on the highway across the same 88 days.
Those three provisions are what stands between an off-road tank and a road tractor:
- 4041(a)(1)(A) catches diesel sold to the operator of a highway vehicle where the terminal rack did not catch it first.
- 4041(b)(1)(B) puts the tax back on fuel sold untaxed for an off-highway business use and then used otherwise.
- 6715(b)(1) prices the dyed-fuel violation at the greater of $1,000 or $10 a gallon, which is the number that has kept the red tank and the road tractor apart.
Read together the package is narrow and very specific. For the rest of the year, the off-road tank can feed the highway tractor.
If you run a yard fleet, a quarry operation, a terminal with a dyed tank for loaders and gensets, that is a real line in your budget. If you buy freight from carriers, it is somebody else's line.
Four cents against seventy nine
Put the deferred rate on the same footing as the surcharge. Section 4041(a)(1)(C) sets it by cross-reference to 4081(a)(2)(A), which is 24.3 cents a gallon, and the cross-reference stops at subparagraph (A), so the tenth of a cent in (B) sits outside it.
Divide by a loaded tractor's fuel economy, call it 5.0 to 6.0 miles a gallon, and the deferral is 4.05 to 4.86 cents a mile.
The truckload surcharge effective Wednesday is 79.0 cents a mile (chart below).
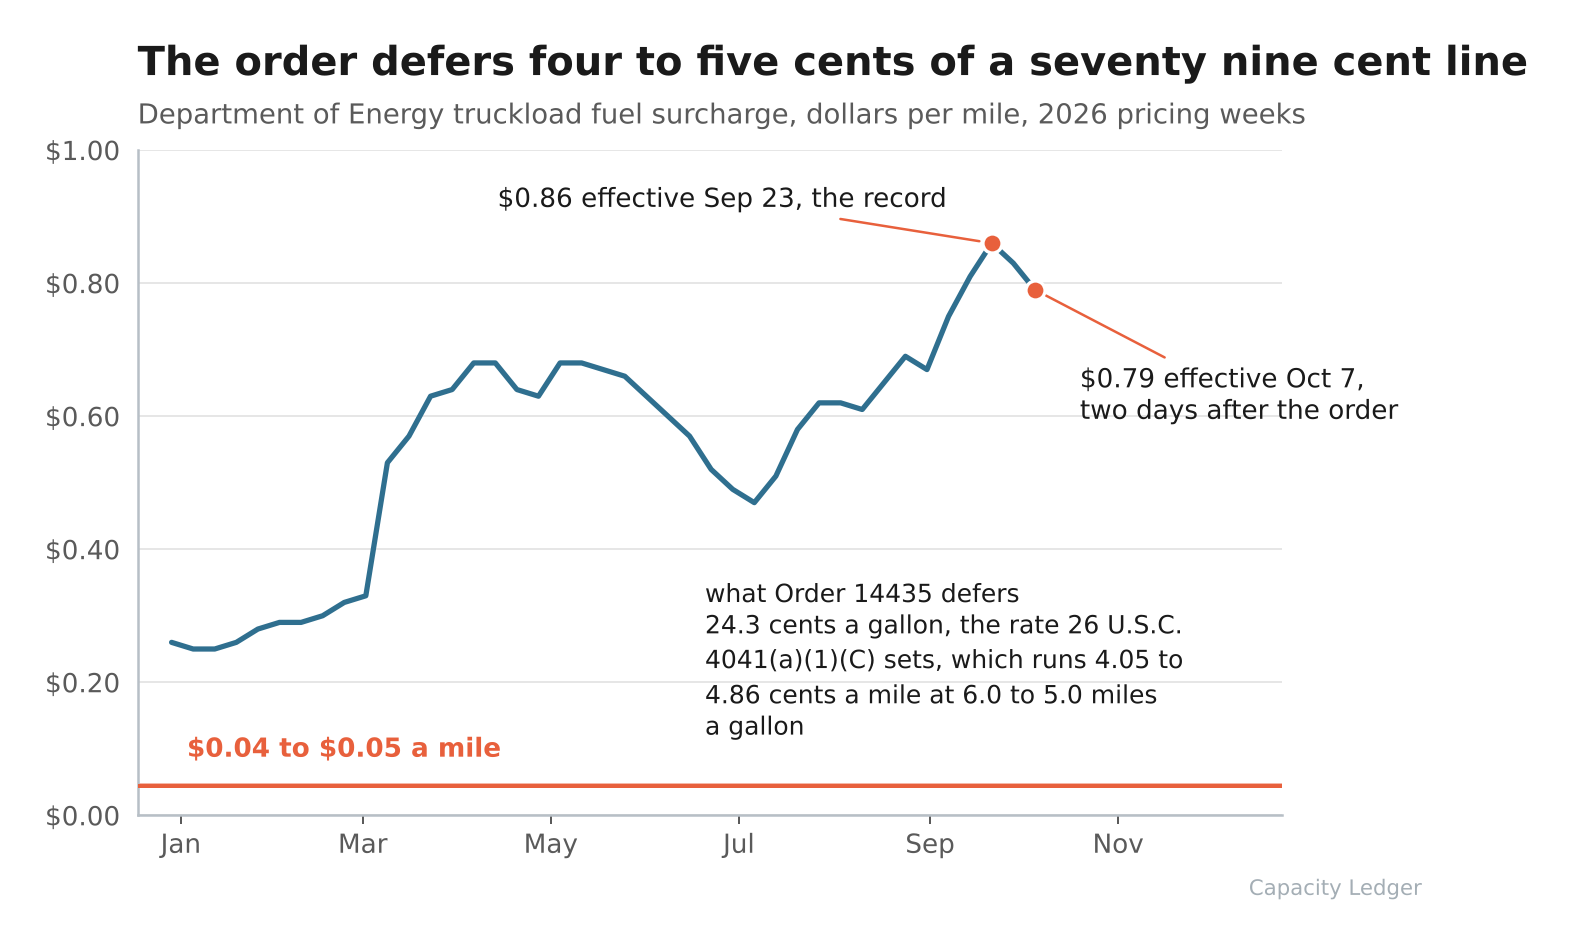
Call it five to six percent of the fuel line on the same mile. Against this year's escalation it is thinner still: the truckload column went $0.25 to $0.79 between the first pricing week of January and the week of October 5, and 4.05 cents is 7.5 percent of that 54 cent move.
On a 500-mile lane, at Wednesday's rates:
- The truckload surcharge is $395.00.
- The deferral, if the tractor burned dyed fuel the whole way, is $20.25.
- On a 45,000 pound load that is $17.56 a ton of surcharge against 90 cents a ton of relief.
And the $20.25 comes back. Section 2 postpones it; section 4 only directs the Secretary to "explore avenues, including legislation" to eliminate the obligation.
Final Thoughts
Three things have to land before the four cents is money, and none of them had as of this morning's issue. Treasury's determination under section 7508A was due within five days of October 5. The implementing guidance section 3 calls for still has to name covered taxpayers and the date the postponed tax comes due. And section 8 asks states to adopt corresponding policies, which concedes that the order reaches none of them, because state diesel tax and state dyed-fuel enforcement sit entirely outside it.
The supply picture the order cites has not moved either. US distillate stocks stood at 105.1 million barrels on October 2, 12.3 percent below the 2021 to 2025 average for the same reporting week, with heating season still in front of them.
So route this one to whoever owns your private fleet and your on-site fuel, and leave the freight budget alone. The line that actually moved on you this year reprices every Wednesday off a number published the Monday before, and nothing signed on October 5 changed which number that is.
Thanks for reading.