 Capacity Ledger
The Propane Discount Started Closing From the Wrong End
Gulf Coast propane and propylene stocks set a record in the same month Mont Belvieu propane went up 22.8 percent. The barrels never left, and the premium arrived anyway. Here is what moved, and which line of a propylene derivative contract it reaches.
EIA's Wednesday file put Gulf Coast propane and propylene stocks at 70.424 million barrels for the week ending September 25. Highest week in a file that starts in January 2015.
Mont Belvieu propane went out that same week at $0.894 a gallon, against $0.680 on August 28.
Record length and a third more money, inside five weeks.
"If the tank has never been fuller, who is bidding the price up?"
The Move
Across the twenty September days EIA has published, Mont Belvieu propane averaged $0.8455 a gallon against August's $0.6883. Up 22.8% on the month.
Only five month-over-month moves have been larger since the series starts in July 1992: January 2021, February 2003, January 2000, December 2000, May 2020.
Four of those five are December, January or February prints. The fifth is May 2020, with WTI climbing off an April monthly average of $16.55.
This one arrived with the tank full.
Gulf Coast stocks sit 37.3% above the 2021 through 2025 average for the same reporting week and 14.6% above the same week last year, and PADD 3 is holding 64.2% of the national total. The US number, 109.647 million barrels, is within a million of the record this series set three weeks earlier.
So scarcity is not available as an explanation, and anyone who offers it to you this quarter is working from a headline rather than from the file.
Where the Premium Showed Up
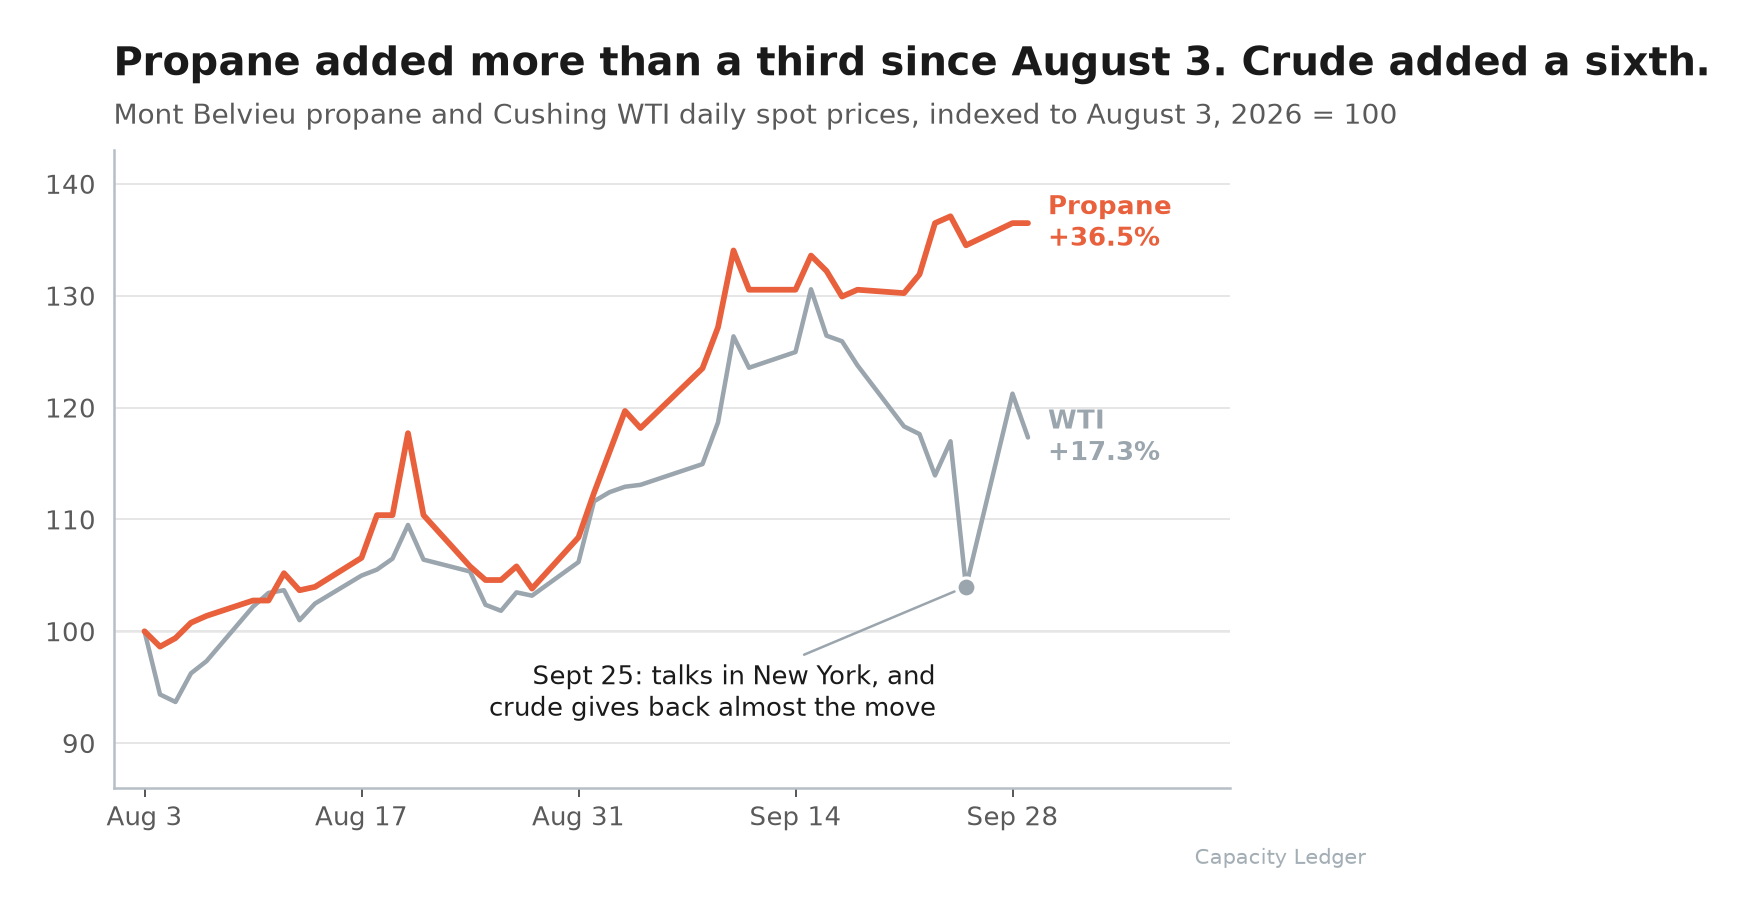
WTI at Cushing went from $81.96 on August 3 to $107.02 on September 15 while US and Iranian forces traded strikes around the Strait of Hormuz. On September 25 diplomats from both sides met in New York for the first time since June, and crude gave it back: $85.23 that session, with front month WTI down 7.5% on the week.
Propane did not go with it.
It printed $0.894 on September 23 and was still $0.894 on September 29. Indexed to August 3, the propane line ends EIA's file at +36.5% and the crude line at +17.3%, and the gap between them opens across the last week of the month (chart below).
The dock is the reason.
US propane exports ran 2,469 thousand barrels a day in the week ending September 18, the third heaviest week since that series starts in June 2010, behind only May 22 and July 3 of this year. The week after, they fell to 1,669.
Mont Belvieu prices off that loading schedule in a way Conway never has. OPIS had the two hubs more than 10 cents a gallon apart in the first week of June, against 2.9 cents in the same week of 2025, with Conway still working for domestic heating demand and Mont Belvieu working for a ship.
The Ratio Is the Part Your Contract Sees
A propane barrel is 42 gallons, so September 29 priced propane at 39.05% of a WTI barrel. The last five published days averaged 39.96%.
August averaged 34.46%.
This desk put 2026 propane at 36.6% of crude on August 22, the cheapest annual average in the thirty-four years the file supports, and said a ratio that far under its own band closes from both ends. It has started closing from the propane end, which is the end that costs you money. Year to date the ratio is 36.46%, still the lowest annual average in the file, so most of the gap is still open.
Two things it changes before the fourth quarter round:
- Feedstock cost is now a real argument on the on-purpose route, and the month is worth 22.8%. The 36.5% headline on the chart is measured off an August 3 base that happened to be a local low. Make the supplier quote the month, and make them quote it against the grade they actually buy.
- Feedstock availability is still not an argument. A propylene derivative supplier pleading tightness is pleading against a district holding the most propane EIA has ever recorded there, a pipeline away from the units that take suction on it.
The index is where the money is.
An escalator written off crude has run in your supplier's favour since March, and it starts running the other way if the New York talks hold. An escalator written off Mont Belvieu now tracks a price that waterborne buyers set.
Neither of those is the feedstock curve for a molecule made in Texas and sold in Texas, which is why the lookback window and the band matter more this quarter than the level does.
Final Thoughts
Six weeks ago the honest read on this market was that the Hormuz shock had landed entirely on the crude leg and left US propane alone, because gas processing economics in Texas do not run through the Strait. That held until the back half of September, when the export bid finally carried the premium across.
The barrels stayed. The price moved anyway.
Those two facts live in the same file, and a contract that can only see one of them is going to keep settling wrong.
Thanks for reading.