The Week Nothing Came Off a Nameplate
No US chemical plant announced a closure in the last four days, and the California WARN file has been empty of chemicals since September 9. What moved instead was permission and ownership: H.B. Fuller put product lines on the block eleven days after pricing $850m at 7.625%, PHMSA refused to let Trinity re-letter tank cars for inhalation-hazard service, and Cliffs idled the galvanizing lines at Stelco.
Four working days of federal filings and state notices, and not one of them took a pound of US chemical capacity offline.
The California WARN file has not carried a chemical site since September 9, and the EDGAR capacity phrases this desk runs every week came back at zero.
The Federal Register's chemical docket since Friday is one correction to an order we already ran.
So the week's real movement happened in two files most buyers never open: who is allowed to move a molecule, and who is going to own the line that makes it.
"If the plant list didn't change, what did?"
A Bond Deal Decided Which Lines Are for Sale
On Monday H.B. Fuller's board unanimously rejected Ancora's second unsolicited, non-binding proposal for the Building Adhesive Solutions business, pitched at $1.2 billion to $1.4 billion in cash.
That part is a governance headline. The sentence after it reaches a sourcing desk.
Fuller said it will "conduct a market check involving select market segments and product lines that are less integral to its portfolio and strategy, with the intent to use any proceeds towards deleveraging," and that it expects to complete that market check by year end 2026.
Ten weeks. More than thirty market segments in the company, and the filing names none of the ones in scope.
Now, why the hurry. Eleven days earlier Fuller priced $850 million of 7.625% senior unsecured notes due 2034, closing on or about October 21, to fund the Advanced Medical Solutions acquisition and retire its 4.000% notes due February 2027.
Call that coupon step what it is: 362.5 basis points.
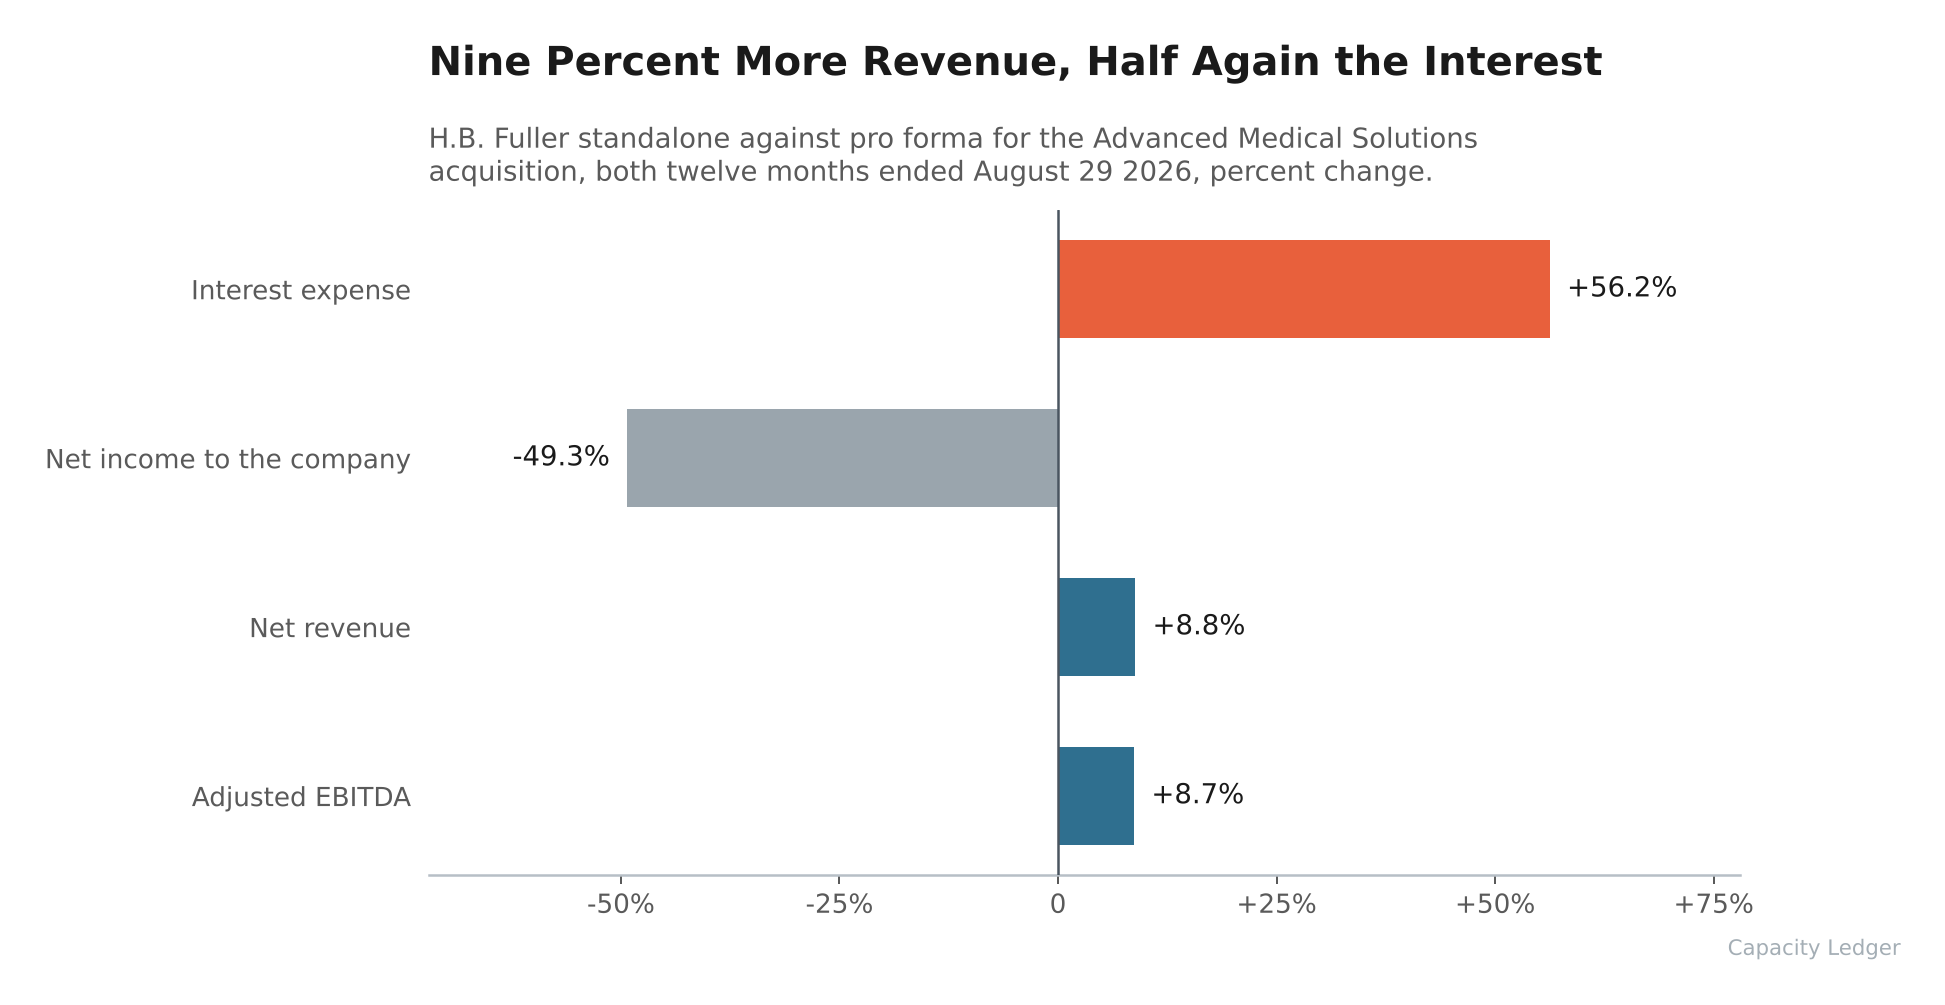
Fuller's own pro forma table, filed two weeks ago, prices the rest. Against the twelve months ended August 29, the combined company carries +8.8% net revenue and +8.7% adjusted EBITDA against +56.2% interest expense, and net income lands at -49.3% (chart below).
Pro forma net total leverage comes out at 4.2x, interest coverage at 3.3x. Monday's deleveraging language is doing the work those two ratios imply.
We covered Fuller's fiscal Q3 on September 24, when pricing ran +7.4% against volume -3.0%. The new fact is a seller of product lines working to a published deadline.
If you buy adhesive from a Fuller segment outside the medical business it just borrowed to acquire, ask your account manager which side of the market check you are on.
The rest of this brief is for subscribers.
The capacity math, the trade-flow read, and what it means for the products you buy.
$50 a month, or $400 a year.
Already a subscriber? Sign in